Why Is the Concave Hurt by Black Swan Events?
Concave exposures are disproportionately harmed by unexpected large events (Black Swans). The more concave an exposure, the more damage from very large deviations, as they have a disproportionately larger effect.
THE IDEA
Why Is the Concave Hurt by Black Swan Events?
Now the idea that has inhabited me all my life—I never realized it could show so clearly when put in graphical form. Figure 13 illustrates the effect of harm and the unexpected. The more concave an exposure, the more harm from the unexpected, and disproportionately so. So very large deviations have a disproportionately larger and larger effect.
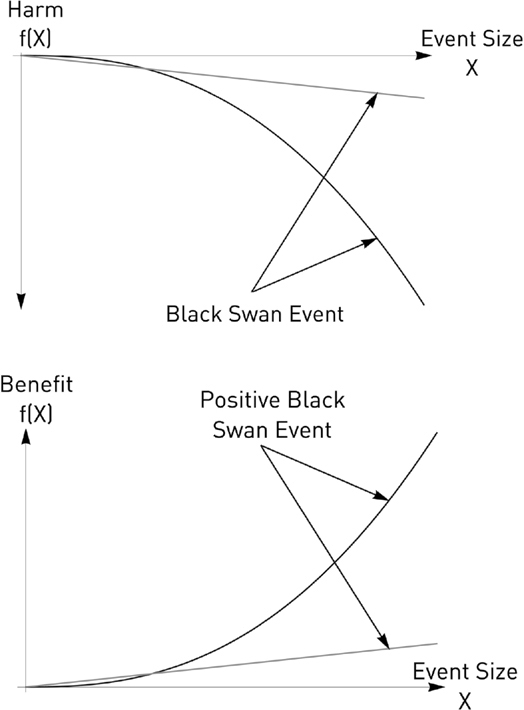
FIGURE 13. Two exposures, one linear, one nonlinear, with negative convexity—that is, concavity—in the first graph, positive convexity in the second. An unexpected event affects the nonlinear disproportionately more. The larger the event, the larger the difference.
Next, let us apply this very simple technique to the detection of fragility and position in the Triad.
When to use it
Assessing the fragility of investment portfolios by analyzing their convexity to market shocks.
Evaluating business models for vulnerability to rare events (e.g., supply chain disruptions, regulatory changes).
Identifying personal risk exposures (e.g., relying on a single income source) and planning for tail risks.
Designing antifragile systems that gain from volatility rather than being harmed by it.
FROM THEORY TO EVERYDAY LIFE
In practice
Concave Financial Exposure
Selling options that insure buyers against a large market decline can create a concave payoff. A small decline may leave the options unexercised, while a sufficiently large decline can produce losses far beyond the premiums collected. The payoff depends on the contracts and any offsetting positions.
Customer Loss and Nonlinear Costs
Losing a major customer creates concentration risk. To establish nonlinear harm, examine the consequences: a small revenue loss might be absorbed, while a larger one could prevent fixed costs from being covered and force a shutdown. The size of a customer alone does not prove concavity.
A MOMENT TO REFLECT
Put it to work.
Identify an exposure in your life (financial, professional, or personal) that is concave. How would a rare, extreme event affect it?
How can you convert a concave exposure into a convex one to benefit from volatility?
Think of a system you rely on. Is it fragile (concave) or robust? What would a Black Swan do to it?
Often confused with
References
- The Black Swan: The Impact of the Highly Improbable — Nassim Nicholas Taleb (2007)
CONTINUE THE CONVERSATION
Source texts
- Antifragile (Nassim Nicholas Taleb)